Successful Instant Transfer Initiated via the Schema
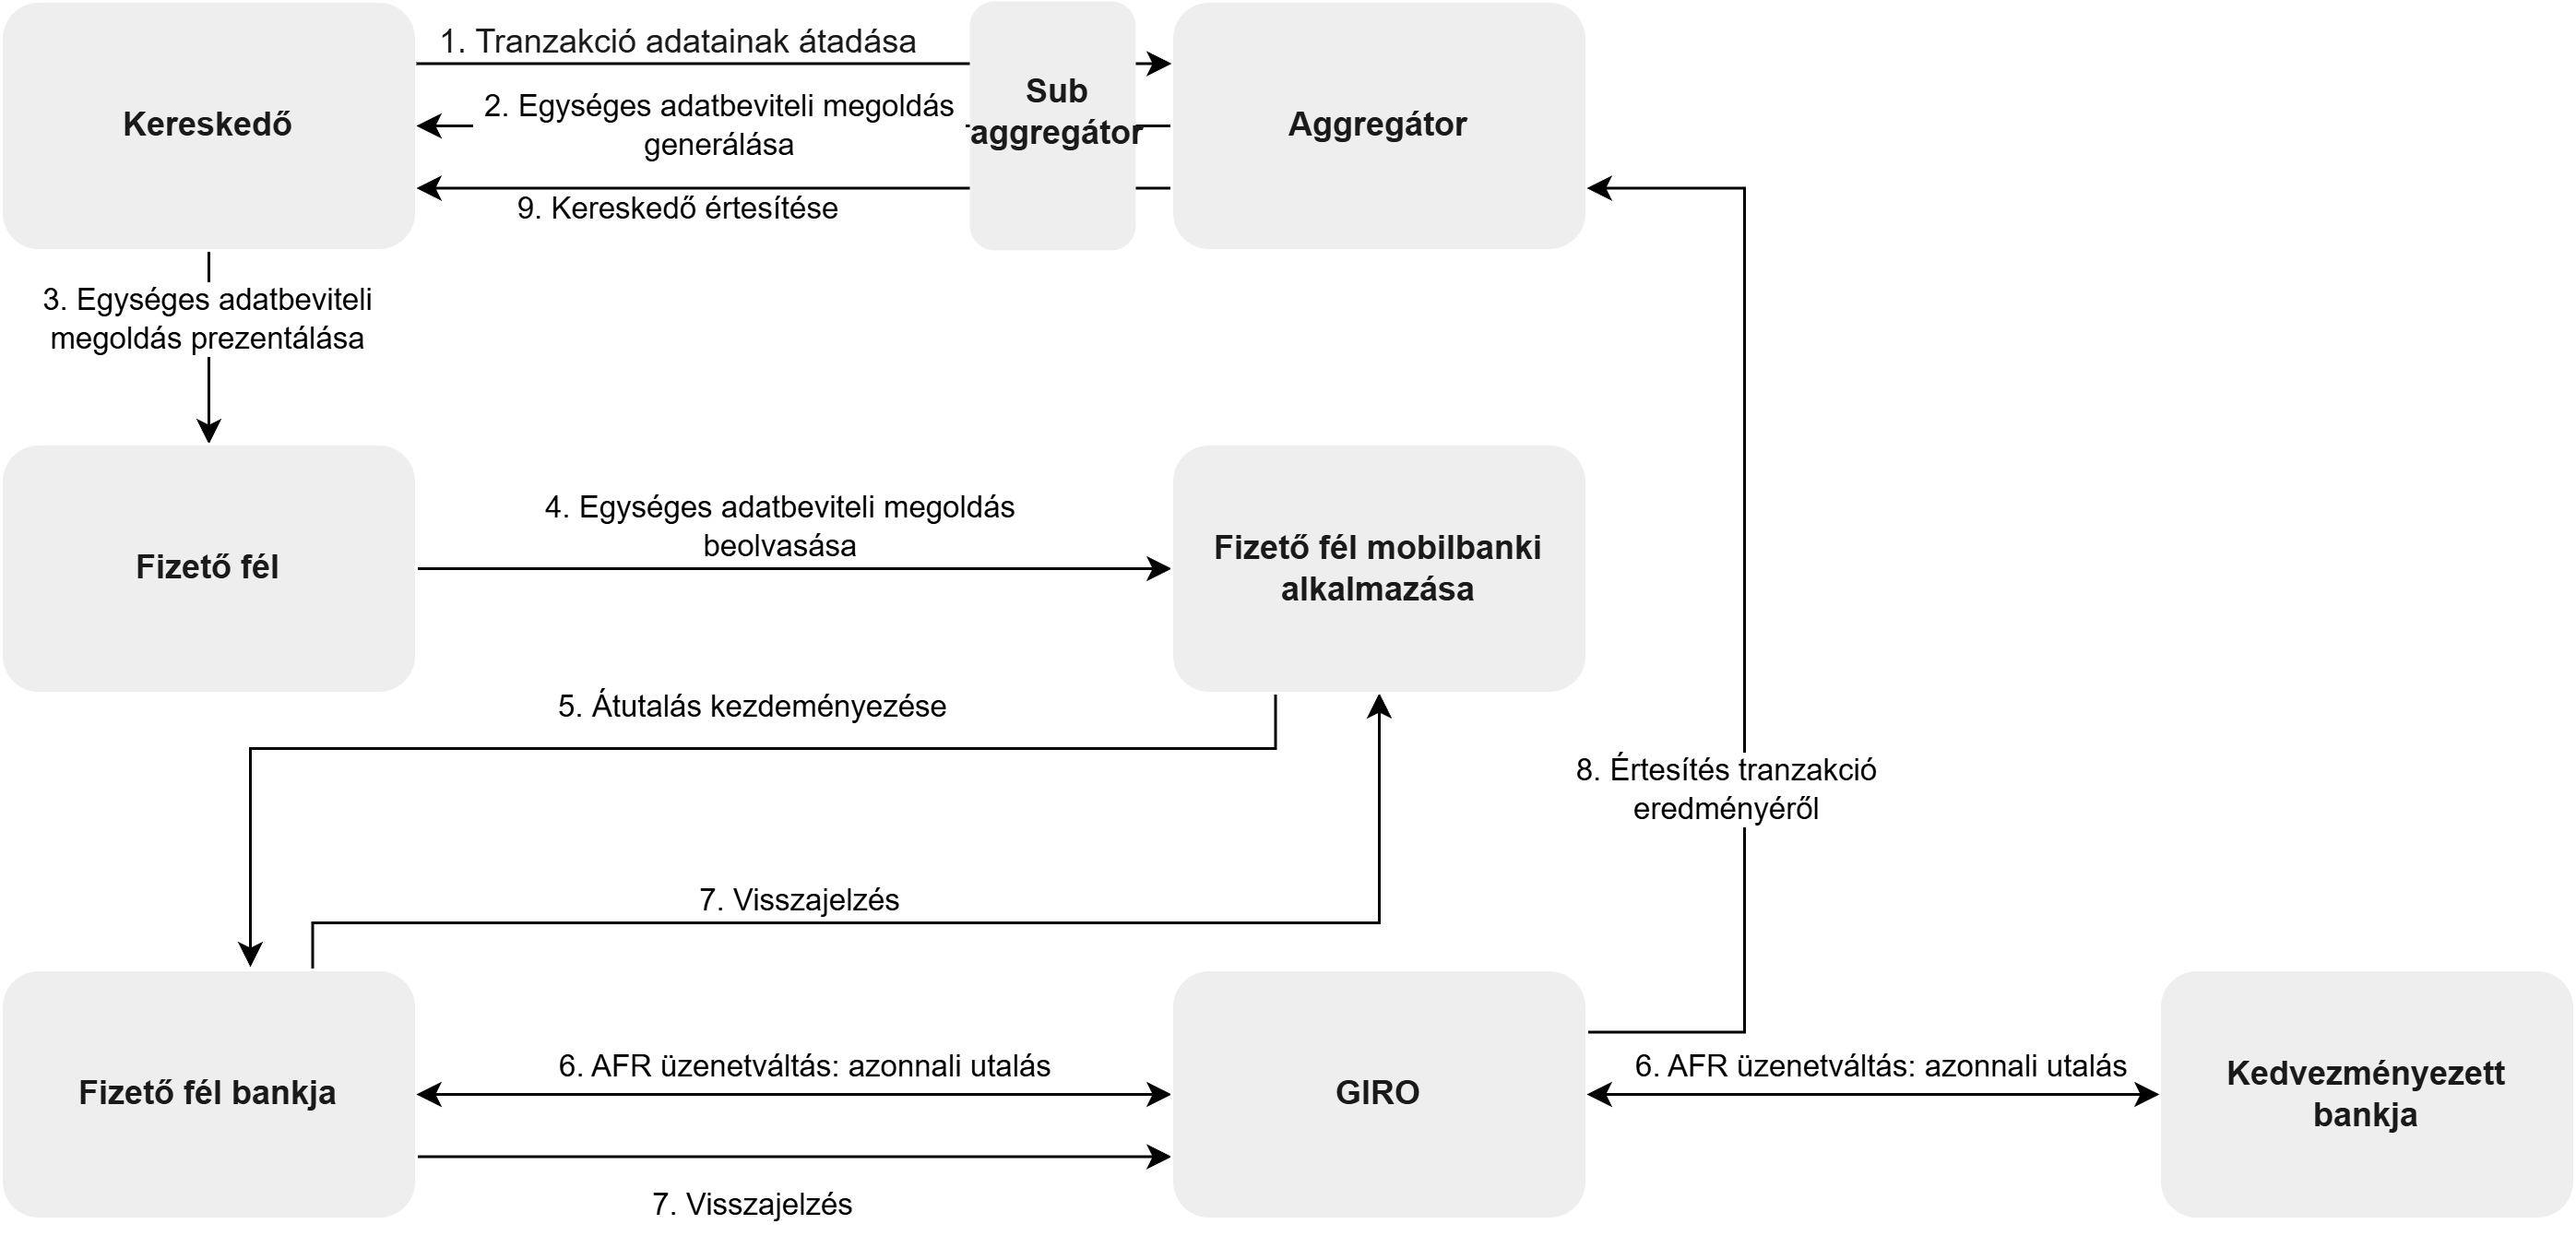
Process steps:
- The merchant's system transmits the current purchase data to the sub-aggregator via an electronic channel, who forwards it to the Aggregator.
- The Aggregator creates the Unified Data Entry Solution (EAM) according to the standard defined in the regulation, which contains the transaction and beneficiary data, and the data is equipped with an authentication code.
- The merchant displays and makes the Unified Data Entry Solution available on their POS system. For invoiced payments, the QR code is printed on the invoice. For webshop purchases, a deeplink is generated which opens the mobile banking application when clicked. For NFC, the merchant's device broadcasts the data.
- The payer scans the Unified Data Entry Solution with their multi-function device. Scanning it launches the pre-installed mobile banking application on the device, since the mobile banking application names that can be launched by scanning the Unified Data Entry Solution on the given operating system are stored in the EAM domain. Alternatively, the payer first logs into the mobile banking application and scans the EAM there.
- Before the payment initiation, the payer's application checks the formal requirements, validity period and authentication code of the Unified Data Entry Solution to verify no changes have been made to the information in it. After this, if strong customer authentication has also been completed, the application initiates the instant transfer towards the payer's bank. If the payer's bank and the beneficiary's bank are the same, an intra-bank transfer takes place. The payer's bank may store the Unified Data Entry Solution for later approval. When approval occurs, all necessary checks must be performed.
- The payer's bank sends the instant transfer message to GIRO. GIRO validates and forwards the message to the beneficiary's bank.
- The beneficiary's bank credits the amount to the beneficiary's account and sends a confirmation to GIRO. GIRO forwards the confirmation to the payer's bank. The beneficiary's bank sends a feedback message to the Aggregator with a payment status of ACCP.
- The Aggregator forwards the feedback to the sub-aggregator, who forwards it to the merchant.
- The merchant's system notifies the payer that the payment was successful.